
There is no single month when every New York City property suddenly becomes a bargain. Spring generally provides buyers with the greatest selection. Winter and late summer may provide more negotiating leverage. Fall often offers a useful balance between fresh inventory and motivated sellers.
The right time for an individual buyer also depends on factors that have little to do with the calendar: financing, available cash, expected length of ownership, preferred neighborhood and whether a suitable property is available.
For most buyers, the best time to buy a home in NYC is when three conditions come together:
- The monthly payment fits comfortably within the household budget.
- The buyer has enough cash for the down payment, closing costs and post-closing reserves.
- A suitable property is available at a price that makes sense relative to comparable sales.
Waiting for the “perfect” season or the lowest possible mortgage rate can cause buyers to miss a good property. At the same time, purchasing simply because a listing appears discounted can be costly if the building, financials or monthly carrying charges are unsuitable.
Quick answer: Shop in spring or early fall if you want the widest selection. Consider late summer or winter if negotiation matters more than choice. Buy when your finances and expected ownership period support the decision.
NYC market snapshot: October 2026
The current market does not fit neatly into a simple buyer’s-market or seller’s-market label.
According to StreetEasy’s September 2026 NYC market analysis, inventory was 4.9% lower than one year earlier, while 21.1% of homes sold above their latest asking price. At the same time, contracts fell 5.4% year over year as higher mortgage rates affected buyer budgets.
Mortgage costs remain an important constraint. Freddie Mac’s Primary Mortgage Market Survey reported an average 30-year fixed rate of 7.32% on October 22, 2026, compared with 6.19% one year earlier. Freddie Mac’s figure is a national average for qualifying mortgage applications, not a quote for a specific NYC buyer or co-op loan.
The practical conclusion is that buyers should not assume all sellers are desperate or that all properties will attract bidding wars. Competition depends on the borough, neighborhood, price range, property condition and building quality.
A well-priced apartment in a desirable building may receive several offers. A property with high monthly charges, dated interiors, restrictive rules or months of unsuccessful marketing may offer considerably more room to negotiate.
When is the best time of year to buy a home in NYC?
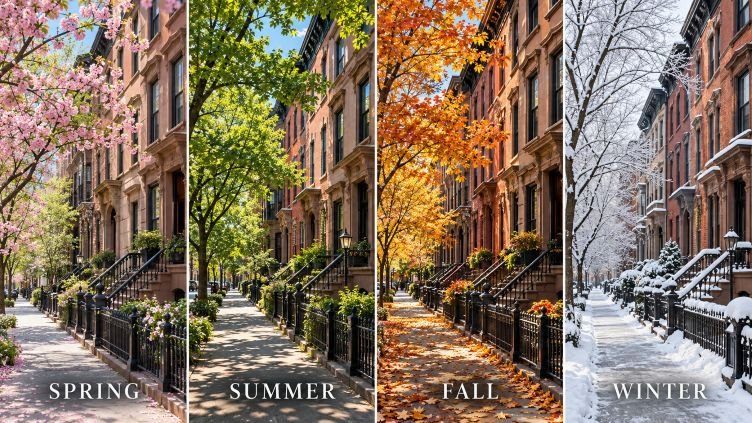
The best season depends on whether your priority is selection, convenience or negotiating power.
| Season | Typical inventory | Buyer competition | Negotiation opportunity | Best suited for |
|---|---|---|---|---|
| Spring | Highest or increasing | Usually strong | Low to moderate | Buyers who want the widest selection |
| Summer | Moderate, often slowing by August | Mixed | Moderate to strong late in the season | Flexible buyers seeking overlooked listings |
| Fall | Fresh September inventory, then gradually declining | Moderate to strong | Moderate | Buyers seeking balance between choice and leverage |
| Winter | Lowest | Usually lower | Often strongest on lingering listings | Buyers prioritizing negotiation over selection |
These are tendencies, not guarantees. Mortgage-rate changes, economic news and neighborhood-specific supply can disrupt the normal seasonal pattern.
Spring: the best season for property selection
The NYC spring buying season usually begins before the weather feels fully springlike. Sellers and listing agents often prepare properties in February and March, with activity building through April and May.
Advantages of buying in spring
- More co-ops, condos and houses generally enter the market.
- Buyers can compare more properties within the same neighborhood.
- Families aiming to move during summer have time to complete the transaction.
- Outdoor spaces, natural light and surrounding streets are easier to evaluate.
- New developments may release additional inventory.
Disadvantages of buying in spring
- Attractive listings can receive competing offers.
- Buyers may have less time to consider a newly listed property.
- Sellers of desirable homes may be less receptive to discounts.
- Open houses can be busy.
- A buyer who is not pre-approved may lose to a better-prepared bidder.
Spring is often the best time to buy if you have highly specific requirements. That may include a particular school district, building type, number of bedrooms, subway line, outdoor space or accessibility feature.
Selection has value. Buying a property that genuinely fits your needs can be more important than obtaining a modest seasonal discount on the wrong home.
Summer: a changing market with an August opportunity
The early summer market can remain active as spring transactions continue. Activity may slow later as buyers, sellers, attorneys and board members take vacations.
August is sometimes called a sleeper month because fewer buyers are actively searching. Listings that failed to sell during spring may still be available, and their owners may be more willing to reconsider price or terms.
Why late summer can favor buyers
- Some spring listings have accumulated substantial days on market.
- Price reductions may have already occurred.
- Open houses may attract fewer buyers.
- Sellers hoping to close before fall may become more flexible.
- Buyers can evaluate whether a listing has failed because of price or a genuine property problem.
The limitation is reduced inventory. A buyer may encounter better negotiating conditions without finding as many suitable properties.
August can be particularly useful for flexible purchasers who are comfortable evaluating older listings and distinguishing a pricing problem from a building, legal or financial problem.
Fall: a balance between selection and leverage
September and October form NYC’s second major listing season. Sellers return after summer, buyers resume their searches and new inventory enters the market.
Fall may offer the best overall balance for many buyers:
- More selection than winter
- Less concentrated activity than peak spring
- Sellers who want to complete a transaction before year-end
- Opportunities to revisit listings that did not sell during spring or summer
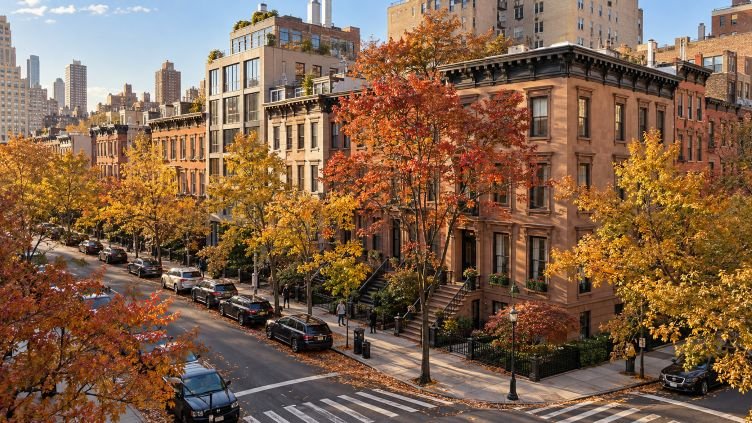
The strongest new fall listings can still attract immediate competition. Negotiating leverage is usually greater on properties that have been available for months, returned to market or undergone several price reductions.
As November approaches, some sellers may withdraw and relist later. Others may prefer to negotiate rather than carry the property into another year. The reason for selling matters more than the season alone.
Thinking about buying a home in NYC?
Find out which neighborhoods, properties and buying periods match your budget and timeline.
Submit the buyer form to receive the 90-Day NYC Home Buyer Readiness Checklist.
Winter: fewer choices but potentially more leverage
December through February normally produces fewer new listings and fewer active buyers. Winter sellers may have a stronger reason for keeping their properties on the market during a slower period.
Possible seller motivations include:
- An employment-related relocation
- An estate or financial deadline
- A property that did not sell during the previous season
- A desire to avoid further carrying costs
- A purchase that depends on selling the current home
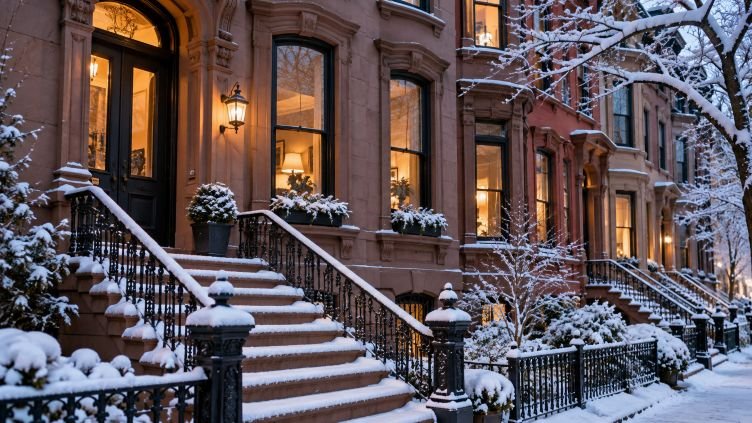
Winter buyers may be able to negotiate more deliberately, particularly on listings with extended days on market. Sellers may also be more receptive to flexible closing dates, repair credits or other reasonable terms.
However, winter is not automatically the cheapest season. A scarce, renovated apartment in a strong building can still attract competition. Inventory may also be too limited for buyers with narrow requirements.
Winter has practical disadvantages. Snow can make it harder to assess roofs and outdoor areas, while shorter days can affect evaluations of natural light. Buyers should also consider holiday schedules, co-op board meetings and delays involving lenders, managing agents or attorneys.
What is the cheapest month to buy a home in NYC?
There is no reliably cheapest month across every NYC neighborhood and property type.
December, January, February and August can offer favorable negotiations because buyer activity may decline. But a lower median price in any month does not necessarily mean comparable homes became cheaper. The mix of properties sold can change from month to month.
For example, a month containing more studio and one-bedroom co-op transactions will show a lower median sale price than a month containing more large condos—even if individual property values did not decline.
A better way to judge value is to compare:
- Recent sales in the same building
- Similar properties within the immediate neighborhood
- Price per square foot, where meaningful
- Monthly common charges or maintenance
- Property condition and expected renovation costs
- Days on market
- Previous price reductions
- Whether the listing was withdrawn and relisted
- The difference between the original and current asking price
Buyers can research recorded transactions through the NYC Department of Finance Rolling Sales Data. The files provide property sales information organized by borough and neighborhood.
The cheapest month is less useful than identifying an overpriced property whose seller has become ready to meet the market.
Is 2026 a good time to buy in NYC, or should you wait until 2027?
For financially prepared buyers who expect to remain in the property for several years, late 2026 can still be a reasonable time to buy. Higher financing costs have reduced some buyers’ budgets, and listings that require work or have remained unsold may offer room for negotiation.
Waiting until 2027 may make sense when:
- The current monthly payment would be uncomfortable.
- Employment or income is uncertain.
- The buyer lacks sufficient closing-cost or emergency reserves.
- The likely ownership period is short.
- A major personal change could alter the required location or property size.
- The buyer needs time to improve credit or reduce other debt.
- Available properties do not meet the buyer’s essential needs.
Waiting solely because rates might fall is a speculative decision. If rates decline, affordability may improve—but more buyers may return, competition may increase and sellers may become less flexible. If rates remain high or rise further, the waiting buyer has not gained the expected financing advantage.
No credible market forecast can guarantee that NYC prices or mortgage rates will be lower in 2027.
The better question is:
Would buying this particular property now leave you financially comfortable even if rates and prices do not move in your favor next year?
If the answer is yes, the purchase deserves consideration. If the transaction depends on an immediate refinancing opportunity or rapid appreciation, the risk is substantially greater.
Should you buy now or wait for mortgage rates to drop?
Mortgage rates influence the monthly payment, qualification amount and total interest cost. They are important, but they should not be the only timing factor.
Consider a simplified example involving a $640,000, 30-year mortgage:
| Illustrative interest rate | Approximate monthly principal and interest |
|---|---|
| 7.25% | $4,366 |
| 6.50% | $4,045 |
| 5.75% | $3,735 |
These figures exclude property taxes, insurance, maintenance, common charges, mortgage insurance and other costs.
A lower rate could produce meaningful savings. The problem is that buyers cannot know when a particular rate will become available or what home prices and competition will look like at that time.
A practical strategy is to:
- Obtain quotes from more than one lender.
- Calculate the payment at the current rate.
- Test whether the budget still works if the rate or monthly charges are slightly higher.
- Negotiate the property based on current market conditions.
- Treat a future refinancing opportunity as a benefit—not a requirement for affordability.
Buyers should also compare lender fees and points. A lower advertised rate may require a significant upfront payment.
How inventory, competition and mortgage rates work together
The best NYC buying opportunities often appear when these three factors do not move in the same direction.
High inventory and manageable competition
This is generally the most favorable combination for buyers. There are enough properties to compare, and sellers cannot assume every listing will receive several offers.
High inventory and high competition
Buyers have choices, but the best-priced homes may move quickly. Spring markets often resemble this environment.
Low inventory and low competition
This can create negotiation opportunities, but buyers may struggle to find the right property. Parts of the winter market can fit this description.
Low inventory and high competition
This is the most difficult environment. A small number of desirable listings receive concentrated attention. Buyers need strong preparation and disciplined price limits.
A citywide market label can hide these differences. Manhattan luxury condos, Queens co-ops and Staten Island houses may behave very differently during the same month.
How to recognize a buyer’s market in NYC
Look beyond headlines and examine the segment in which you intend to purchase.
Useful signs include:
- Inventory rising faster than contract activity
- Longer marketing periods
- Frequent price reductions
- Properties selling below their latest asking prices
- Fewer competing offers
- Relisted or returned-to-market properties
- Greater seller willingness to discuss credits or repairs
- Similar homes available in the same building or nearby
Signs of a seller’s market include:
- Falling inventory
- Short marketing periods
- Offers due shortly after the first open house
- Multiple bids
- Sales above asking price
- Limited comparable alternatives
- Sellers rejecting contingencies or seeking highly flexible terms
Days on market require interpretation. A long marketing period can mean a seller is becoming motivated, but it can also signal excessive monthly charges, poor condition, restrictive building policies, financing problems or unrealistic expectations.
Can buyers get better deals on older listings?
Yes, but an old listing is not automatically a good deal.
Before making an offer, investigate:
- The original listing date
- Asking-price history
- Whether the property was withdrawn and relisted
- Previous accepted offers that failed
- Comparable closed sales
- Building financial statements
- Planned assessments
- Litigation or financing restrictions
- Renovation requirements
- Seller motivation and preferred closing date
A carefully structured offer can address more than price. Depending on the transaction, buyers may discuss closing dates, included fixtures, repair credits, financing contingencies and costs the seller is permitted to cover.
The strongest negotiation is based on evidence. An aggressive offer unsupported by comparable sales may be ignored, while a well-documented offer can start a serious conversation.
Does the best time differ across NYC’s five boroughs?
Yes. Every borough contains several distinct markets, so even borough-wide trends should be treated as a starting point.
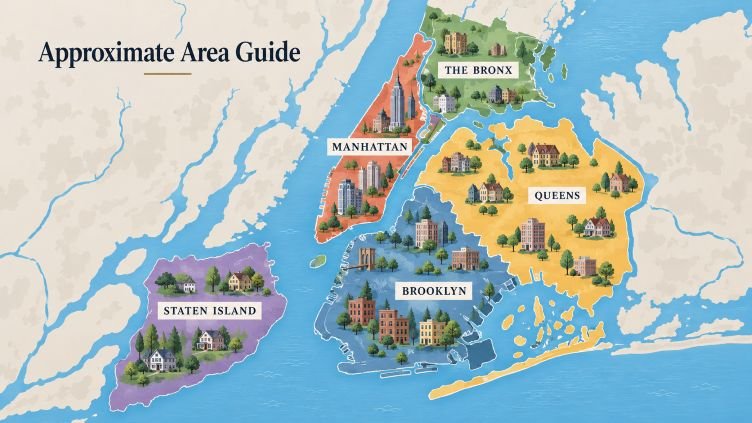
Manhattan
Manhattan usually has pronounced spring and fall listing seasons. Buyers seeking a large selection of co-ops and condos may prefer these periods. Late summer and winter can offer leverage on properties with high carrying costs or extended marketing times.
Citywide data does not indicate that all Manhattan properties are appreciating at the same pace. The NYC Comptroller’s October 2026 economic update reported that overall NYC sales prices were nearly unchanged from the prior year and slightly below pre-pandemic levels, with different results across Manhattan, Brooklyn and Queens.
Brooklyn
Popular Brooklyn neighborhoods can remain competitive beyond the traditional spring peak. Townhouses and well-located family-size apartments have limited substitutes, so waiting for winter does not guarantee a discount.
Buyers with flexible neighborhood boundaries may gain more from expanding their search than from waiting for a different season.
Queens
Queens offers a varied mix of co-ops, condos and houses. Market conditions can differ sharply between neighborhoods and property types.
StreetEasy reported that Queens contract activity rose year over year in September 2026 even as new contracts fell in Manhattan and Brooklyn. That is a useful reminder that a citywide slowdown may not apply to every borough.
The Bronx
The Bronx may provide relatively attainable entry points, but supply, property condition and financing eligibility can vary significantly. Buyers evaluating houses should budget for inspections and future repairs rather than comparing purchase prices alone.
Staten Island
Staten Island contains a larger share of one- and two-family houses than many NYC buyer searches. Weather can make winter inspections more complicated, while spring may provide a better view of roofs, drainage, landscaping and exterior condition.
The right timing may depend more on available house inventory and the buyer’s inspection requirements than on apartment-market seasonality.
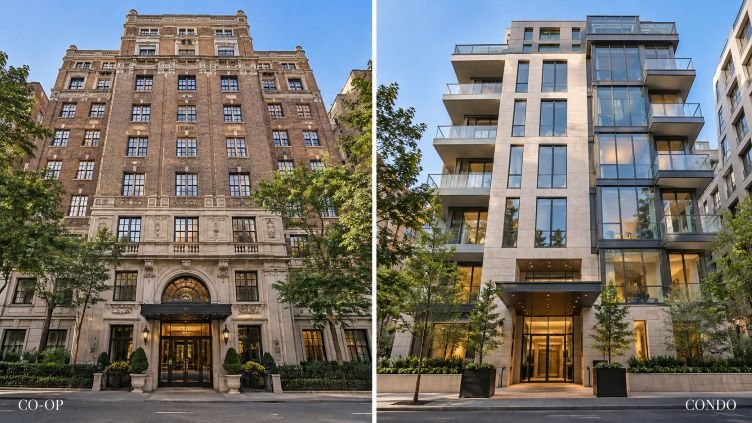
Is timing different for a co-op and a condo?
Yes.
Timing a co-op purchase
Co-op buyers must account for:
- Board application preparation
- Financial-document review
- Post-closing liquidity requirements
- Board interview scheduling
- Building-specific financing rules
- Restrictions on subletting, pets or renovations
A slower season may give buyers more negotiating leverage, but it does not reduce the importance of board eligibility. Buyers should review financial requirements before making an offer.
Timing a condo purchase
Condos generally allow broader buyer and investor participation. Well-located condos may attract local buyers, investors and international purchasers, which can make demand less seasonal.
New-development sponsors may offer concessions, common-charge credits or closing-cost assistance without reducing the recorded sale price. Buyers should compare the economic value of the complete package and have an attorney review the offering plan and contract.
When is the best time for first-time buyers?
The best time is after preparation but before urgency takes control of the decision.
A first-time buyer should ideally have:
- A realistic monthly housing budget
- Mortgage pre-approval
- Funds for the down payment and closing costs
- Emergency savings
- An understanding of co-op and condo differences
- A list of essential and optional requirements
- An attorney and inspector selection strategy
- Time to compare properties without rushing
Qualified purchasers can also investigate the NYC HomeFirst Down Payment Assistance Program. The program currently describes assistance of up to $100,000 toward eligible down-payment or closing expenses for approved first-time purchasers of qualifying homes, condos and co-ops in the five boroughs. Income, education, lender, property and occupancy requirements apply.
Buyers interested in assistance should start early. Program approval, counseling and property requirements can affect the buying timeline.
How far in advance should you prepare?
A 90-day preparation period is a useful minimum for many buyers, although credit improvement or assistance programs may require longer.
Three to six months before searching
- Review credit reports.
- Reduce expensive debt where practical.
- Build closing-cost and emergency reserves.
- Compare property types and boroughs.
- Attend required homebuyer education if pursuing assistance.
One to three months before searching
- Obtain mortgage pre-approval.
- Collect tax returns, bank statements and employment documents.
- Establish a maximum monthly payment.
- Identify target neighborhoods.
- Interview buyer representatives and attorneys.
During the active search
- Track new listings and price reductions.
- Review comparable sales.
- Visit properties at different times of day.
- Ask for building and monthly-cost information.
- Update the pre-approval if rates or finances change.
Preparation gives buyers the ability to act when the right opportunity appears, regardless of whether it arrives in February, May or October.
How long does buying a home in NYC take?
The timeline begins before the first showing and continues after offer acceptance.
A straightforward condo or house transaction may take approximately 45–90 days after contract signing, depending on financing, title review and the parties’ readiness. A co-op can take longer because the buyer must assemble a board package and receive approval.
New development, estate sales, lender complications and title issues can extend the process.
Seasonality may also influence timing. Holiday schedules, summer vacations and limited co-op board meetings can delay approvals. A buyer hoping to move by a specific date should work backward and build in a buffer.
Does buying at the end of the year provide tax advantages?
Closing before year-end does not automatically create a worthwhile tax benefit.
Certain mortgage interest, points or real estate taxes may receive tax treatment depending on the buyer’s circumstances and applicable rules. Other closing expenses may be added to the property’s tax basis rather than deducted immediately.
The IRS explains the general treatment in Publication 530, Tax Information for Homeowners. Buyers should consult a tax professional before changing a closing date for tax reasons.
A rushed December closing can create more risk than benefit if the buyer has not completed due diligence or reviewed final figures.
How much can you save by buying during the off-season?
There is no reliable citywide off-season discount.
The potential saving depends on:
- Purchase price
- Property type
- Seller motivation
- Days on market
- Comparable sales
- Competing offers
- Required renovations
- Monthly carrying costs
- Financing rate
- Negotiated credits or concessions
Suppose a buyer negotiates a $25,000 price reduction but accepts monthly charges that are $500 higher than comparable properties. Over five years, that difference equals $30,000 before considering increases.
A lower purchase price is valuable, but buyers should compare total ownership cost rather than measuring the deal only by the discount from the asking price.
A practical buy-now-or-wait checklist
Buying now may be reasonable when:
- You expect to remain in the home for several years.
- The monthly payment works at today’s rate.
- You have sufficient cash after closing.
- Your employment and income are stable.
- The property meets your important long-term needs.
- The price is supported by comparable sales.
- You have completed legal, building and physical due diligence.
Waiting may be safer when:
- Buying would consume nearly all available savings.
- The payment works only if rates fall soon.
- You expect to relocate in the near future.
- Your credit or debt position is likely to improve materially.
- You are purchasing because of pressure or fear of missing out.
- You have not compared property types or neighborhoods.
- The available homes do not fit your requirements.
Are you ready to buy—or would waiting put you in a stronger position?
Share your budget, preferred borough, property type and timeline to receive a more focused NYC buying plan.
One short buyer form. You will also receive the 90-Day NYC Home Buyer Readiness Checklist.
Frequently asked questions
What is the best month to buy a home in NYC?
There is no guaranteed best month. Buyers often find more negotiating opportunities in January, February and August, while March through May and September through October generally provide more inventory.
What is the worst time to buy a home in NYC?
The worst time is when a buyer is financially unprepared, has not completed due diligence or feels pressured to exceed a sensible budget. A competitive season is manageable when the buyer has preparation and discipline.
Is winter the cheapest time to buy in NYC?
Winter may produce motivated sellers and less competition, but limited inventory can offset that advantage. A desirable home can still attract several offers.
Are bidding wars more common in spring?
They can be, particularly for well-priced properties in desirable buildings and neighborhoods. Competition can also remain strong during summer or fall when inventory is limited.
Is August a good time to buy an apartment in NYC?
August can provide opportunities on spring listings that remain unsold. Buyers may encounter fewer competitors, but there will usually be fewer new properties from which to choose.
Should I wait for NYC prices to fall?
A broad price decline is not guaranteed and may not occur in the neighborhood or property type you want. Evaluate current comparable sales, monthly costs and personal affordability instead of relying on a citywide forecast.
Should I wait for mortgage rates to fall?
Wait if today’s payment is unaffordable. If the payment is comfortable and the property is suitable, a future rate reduction should be treated as a possible refinancing opportunity rather than a necessary part of the buying plan.
When should I get pre-approved?
Ideally, obtain pre-approval shortly before beginning a serious search. Ask the lender how long the approval remains valid and what documents will be required for an update.
Is fall better than spring for NYC buyers?
Spring usually provides more inventory. Fall can offer a better balance between selection and negotiation, particularly on properties that were listed earlier in the year.
How do I know whether a listing is negotiable?
Review days on market, price reductions, comparable sales, relisting history, property condition and competing inventory. Your representative can also ask about the seller’s timing and priorities without assuming the seller will accept a steep discount.
The best time is when preparation meets opportunity
Seasonality matters in New York City, but it should guide a buying strategy rather than dictate it.
Spring is generally the selection window. Late summer and winter can become value windows. Fall frequently provides a practical balance between the two. None of these periods protects a buyer from overpaying for the wrong property or missing a strong opportunity while waiting for an ideal month.
The best time to buy a home in NYC is when your financing is secure, your reserves are adequate, your expected ownership period makes sense and a suitable property is available at a defensible price.
Start your NYC home search with a clear timeline.
Tell us what you want to buy, where you want to live and when you hope to move.
Complete the buyer form to request matching opportunities and your free readiness checklist.
Market information was reviewed on October 25, 2026. Mortgage rates, listing inventory, assistance programs and market conditions can change. Buyers should obtain current property, financing, legal and tax guidance before making a purchase.