
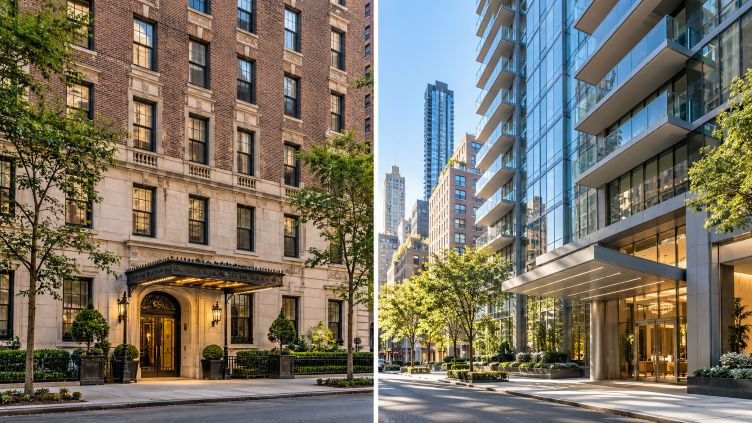
For most buyers seeking a straightforward rental investment in New York City, a condo is generally the better choice. Condos usually allow more flexibility when renting, reselling, financing, or purchasing through an LLC. They are also more accessible to foreign and out-of-state investors.
A co-op can still be a worthwhile investment when the apartment is purchased at an attractive price, the building permits subletting, and the buyer plans to occupy the unit for part of the ownership period. Co-ops usually have lower purchase prices and lower buyer closing costs, but their board rules can limit rental income and resale flexibility.
The real answer to NYC co-op vs condo: what’s better for investment? depends on the building—not merely the ownership label. Before buying, an investor should examine subletting rules, monthly charges, taxes, financing requirements, building finances, rental demand, resale history, and the expected holding period.
Quick Answer
Choose an NYC condo if your main objective is rental income, flexible ownership, easier resale, or buying through an LLC.
Consider an NYC co-op if your priority is a lower purchase price, you expect to occupy the apartment, and the building’s subletting rules support your investment plan.
Condos are usually better for pure investors. Co-ops can work for value-oriented owner-investors, but only after the proprietary lease and building rules have been carefully reviewed.
NYC Co-op vs Condo Investment Comparison
| Investment factor | NYC co-op | NYC condo |
|---|---|---|
| What the buyer owns | Shares in a corporation plus a proprietary lease | The individual apartment as real property |
| Typical purchase price | Usually lower | Usually higher |
| Down payment | Often higher and building-specific | Frequently more flexible |
| Buyer approval | Detailed board package and interview are common | Usually limited to waiver of right of first refusal |
| Rental flexibility | Frequently restricted | Usually more flexible |
| Short-term rentals | Subject to NYC law and building rules | Subject to NYC law and building rules |
| Monthly expenses | Maintenance generally includes building taxes | Common charges plus separate property taxes |
| Mortgage recording tax | Generally not charged on a co-op loan | Applies when a condo mortgage is recorded |
| Title insurance | Usually not purchased like condo title insurance | Normally part of a financed or professionally advised purchase |
| LLC ownership | Frequently prohibited or difficult | More commonly permitted |
| Foreign buyers | Often face additional board or financial hurdles | Generally more accessible |
| Resale process | Buyer may need board approval | Usually simpler |
| Best suited for | Owner-occupants and selective long-term investors | Rental, international, and flexibility-focused investors |
StreetEasy’s 2026 buyer guide reports that condos cost about 10% more on average after accounting for square footage. It also notes that condos generally provide more flexibility for subletting, resale, and pied-à-terre use. Individual buildings can depart significantly from these averages. Read StreetEasy’s co-op and condo comparison.
What Is the Ownership Difference Between a Co-op and a Condo?
The ownership structure influences nearly every part of the investment.
Buying an NYC co-op
When you purchase a co-op, you do not receive a deed to the apartment. You purchase shares in the corporation that owns the building. Those shares are connected to a proprietary lease giving you the right to occupy a specific unit.
Because the corporation owns the building, its board can impose detailed financial, occupancy, renovation, resale, and subletting requirements, subject to applicable law.
Buying an NYC condo
A condo buyer receives ownership of the individual apartment and an interest in the building’s common elements. The transaction resembles a conventional real-property purchase more closely than a co-op acquisition.
A condo board normally has a right of first refusal rather than broad co-op-style purchaser approval. If the board exercises that right, it must generally purchase the unit on the terms negotiated with the outside buyer. In most ordinary resales, the board waives the right and the sale proceeds.
Ownership structure alone does not determine return. It determines how freely the investor can operate the property.
Why Are NYC Co-ops Cheaper Than Condos?
NYC co-ops are generally cheaper because investors and other flexibility-focused buyers place a premium on the rights commonly associated with condo ownership.
A co-op’s lower price may reflect:
- Restrictions on subletting
- Board approval requirements
- Higher down-payment requirements
- Post-closing liquidity requirements
- Limits on pied-à-terre use
- Restrictions on LLC, trust, or corporate ownership
- More demanding resale procedures
- A smaller pool of qualified future buyers
Some co-ops sell for substantially less than comparable condos, but there is no universal 10%–40% discount. The gap depends on location, condition, amenities, building finances, rental rules, and buyer demand.
The lower purchase price may improve the investor’s cost basis. However, that advantage matters only when the building permits the intended use.
A deeply discounted co-op that cannot be rented may be a poor choice for a buy-to-rent investor.
Are NYC Condos Better for Rental Income?
In most cases, yes. Condos usually provide a clearer path to long-term rental income.
A condo building may require:
- A lease application
- Tenant background information
- Move-in deposits
- Minimum lease terms
- Proof of insurance
- Board processing fees
- Compliance with building rules
Those requirements can add time and expense, but many condo buildings permit owners to rent repeatedly without requiring an owner-occupancy period.
A co-op may restrict rentals by:
- Prohibiting subletting entirely
- Requiring several years of owner occupancy
- Allowing rentals only for a limited number of years
- Imposing annual sublet fees
- Requiring board approval for every tenant
- Limiting the total number of sublet apartments
- Requiring a hardship exemption
- Reserving the right to amend rental rules
A rule such as “two years of subletting during any five-year period” is common enough to investigate, but it is not a citywide standard. Every co-op establishes its own policies through its proprietary lease, bylaws, and house rules.
The document investors must read
Never rely only on a listing description saying that a building is “investor-friendly.”
Your attorney should review:
- Proprietary lease or condominium declaration
- Bylaws
- House rules
- Offering plan and amendments
- Board minutes
- Current subletting policy
- Sublet fees
- Lease-duration requirements
- Pending rule changes
The New York Attorney General recommends reviewing the offering plan and ensuring that important representations are included in the written purchase documents. See the Attorney General’s guidance for co-op and condo buyers.
Compare NYC Co-ops and Condos That Match Your Budget
Tell us your preferred neighborhood, purchase budget, property type, and investment plans. We’ll help you explore suitable NYC properties through one buyer inquiry form.
Can You Use an NYC Condo for Short-Term Rentals?
Buying a condo does not automatically give the owner the right to operate a short-term rental.
NYC rules generally prohibit renting an entire apartment or home for fewer than 30 consecutive days. For a lawful hosted stay of fewer than 30 days, the permanent occupant must remain present, no more than two paying guests are permitted, and the host must satisfy registration and other requirements.
The rule applies to owners and tenants, including people living in condos and co-ops. A building can impose rules stricter than the city’s minimum requirements.
Investors should review the NYC Office of Special Enforcement’s short-term rental guidance before assuming that Airbnb-style income is possible.
For most NYC apartment investors, the analysis should focus on lawful leases of 30 days or longer and the building’s minimum lease term.
Do NYC Condos Appreciate Faster Than Co-ops?
Condos often have a broader buyer pool, which can support liquidity and resale demand. Potential condo buyers may include:
- Local owner-occupants
- Domestic investors
- Foreign buyers
- LLC and trust purchasers
- Pied-à-terre buyers
- Parents buying for children
- Buyers seeking rental flexibility
Co-ops can exclude or discourage several of these categories through their financial and occupancy rules.
That does not mean every condo appreciates faster than every co-op. Appreciation depends on:
- Purchase price
- Neighborhood
- Unit size and layout
- Condition and renovations
- Building finances
- Monthly carrying costs
- Assessments
- Amenities
- New construction nearby
- Rental and resale restrictions
- Supply of competing properties
- Market conditions at the time of sale
A well-managed co-op purchased below comparable value may outperform an overpriced condo. A condo with expiring tax benefits, unusually high common charges, construction defects, or excessive investor ownership can underperform.
Use the StreetEasy Data Dashboard to review current price trends, inventory, and market conditions. Its price indices track resale prices across condos, co-ops, townhouses, and single-family homes.
Which Has Better Resale Value: A Co-op or Condo?
Condos generally offer greater resale flexibility because the next buyer usually faces fewer ownership and approval restrictions.
An investor selling a co-op may lose potential buyers who:
- Cannot meet the building’s down-payment requirement
- Lack the required post-closing liquidity
- Need a guarantor
- Plan to use the home as a pied-à-terre
- Want to buy through an LLC
- Intend to rent the apartment
- Do not want to complete an extensive board package
Co-op boards must still comply with federal, state, and local fair-housing laws. Housing providers, including co-op and condo boards, cannot discriminate based on legally protected characteristics. Review the New York Attorney General’s fair-housing guidance.
A condo’s larger potential buyer pool can improve liquidity, but resale is never guaranteed. Price, condition, carrying costs, and the building’s financial health remain decisive.
Maintenance Costs Versus Condo Common Charges
Monthly charges must be compared carefully because co-op and condo statements are structured differently.
Co-op maintenance
A co-op’s maintenance charge commonly includes:
- The shareholder’s portion of building property taxes
- Building operating expenses
- Staff and management
- Common-area insurance
- Heat or water, depending on the building
- Payments connected with the building’s underlying mortgage
- Contributions to reserves
Condo common charges
Condo common charges commonly cover:
- Building operations
- Staff and management
- Amenities
- Common-area maintenance
- Building insurance
- Contributions to reserves
Condo owners normally pay property taxes separately.
A co-op with $1,800 monthly maintenance cannot be compared directly with a condo charging $1,100 in common charges. The condo’s separate property-tax bill must be added first.
Expenses investors should include
Calculate the property’s potential return using:
- Mortgage payments
- Maintenance or common charges
- Property taxes
- Homeowners or landlord insurance
- Vacancy
- Leasing commissions
- Repairs and appliance replacement
- Managing-agent fees
- Sublet charges
- Move-in fees
- Assessments
- Legal and accounting expenses
- Expected capital projects
A low monthly fee is not necessarily good. It may indicate that a building is underfunding reserves or postponing necessary work.
What Are the Closing-Cost Differences?
Co-op buyers generally face lower closing costs than financed condo buyers.
Co-op buyer costs may include
- Attorney’s fee
- Lender expenses
- UCC lien search and filing
- Recognition agreement
- Building application charges
- Move-in deposits
- Appraisal
- Mansion tax when applicable
- Building-specific fees
Because a co-op loan is secured by shares and a proprietary lease rather than a mortgage recorded against real property, it generally does not incur the mortgage recording tax applied to a financed condo purchase.
Condo buyer costs may include
- Attorney’s fee
- Title search and title insurance
- Mortgage recording tax when financing
- Lender expenses
- Appraisal
- Inspection
- Condo application charges
- Move-in deposits
- Mansion tax when applicable
- New-development transfer taxes or sponsor costs when contractually shifted to the buyer
New York State imposes mortgage recording tax on mortgages recorded against real property, with additional local tax in New York City. Review the New York State mortgage recording tax guidance.
The lower closing cost of a co-op can improve the initial investment calculation, but it does not compensate for rental restrictions that prevent the planned income strategy.
What Is a Co-op Flip Tax?
A flip tax is a building-imposed transfer fee paid when a co-op or condo unit is sold. Despite its name, it is not a government tax.
Depending on the building, the fee might be:
- A percentage of the sale price
- A percentage of the seller’s profit
- A fixed amount per co-op share
- A flat fee
The governing documents specify whether the buyer or seller pays it. Investors should include the fee in their projected exit costs because it can reduce net profit when the property is resold.
Do Condos and Co-ops Pay the Mansion Tax?
New York’s additional real estate transfer tax, commonly called the mansion tax, applies to qualifying residential transactions of $1 million or more. The definition includes both individual condominium units and cooperative apartment units.
The base tax begins at 1%, with higher rates applying at higher purchase-price tiers under current law. Buyers should obtain a property-specific closing estimate from a New York real-estate attorney or tax professional.
Are Property Taxes Different?
Condo owners receive an individual property-tax bill. Co-op shareholders generally pay their portion of the building’s property taxes through monthly maintenance.
Qualifying primary-residence owners may benefit from the NYC Cooperative and Condominium Property Tax Abatement, subject to eligibility and building-level filing requirements. An apartment held strictly as an investment may not receive the same primary-residence treatment.
Review current eligibility through the NYC Department of Finance co-op and condo abatement information.
Financing and Down-Payment Requirements
Co-ops frequently impose stricter financial rules than mortgage lenders.
Depending on the building, a co-op may require:
- A 20%–50% down payment
- A maximum debt-to-income ratio
- One or two years of post-closing liquidity
- Detailed tax returns
- Employment verification
- Bank and brokerage statements
- Personal and professional reference letters
These are common market ranges, not citywide legal requirements. Some co-ops accept lower down payments, while others permit only limited financing or require cash purchases.
Condos frequently allow more flexible financing, but lenders also evaluate the building. A loan may encounter problems if the condominium has inadequate insurance, litigation, poor reserves, excessive commercial space, high investor concentration, or other project-level concerns.
For an investor, a lower down payment can improve cash-on-cash returns but also increases debt service and exposure to interest-rate changes.
Can a Co-op Board Reject an Investor?
A co-op board can exercise considerable discretion when reviewing a buyer, provided it complies with fair-housing and other applicable laws.
An investor may encounter difficulty when:
- The building prioritizes owner occupancy
- Subletting is prohibited or limited
- LLC purchases are not permitted
- The proposed financing exceeds building limits
- Post-closing reserves are insufficient
- The financial package does not meet published expectations
The purchase contract should address the consequences of board rejection and the return of the contract deposit. Buyers should obtain legal advice about the specific agreement.
How Does a Condo’s Right of First Refusal Work?
A condo board normally does not approve or reject a buyer through the same process used by a co-op board.
Instead, the condominium reviews the proposed transaction and typically issues a waiver of its right of first refusal. To exercise the right, the condominium would generally need to purchase the unit on the same material terms offered by the outside buyer.
The review still takes time, and buyers must submit the required documents. However, the process is usually less intrusive than co-op board approval.
Can an LLC Buy an NYC Co-op or Condo?
An LLC can commonly purchase a condo if the condominium documents permit it and the buyer satisfies disclosure and compliance requirements.
Many co-ops require ownership in an individual’s name and prohibit or restrict LLCs, corporations, trusts, and other entities. Some investor-friendly co-ops permit entity ownership, but buyers should never assume this.
Entity ownership can have legal, financing, insurance, tax, and disclosure consequences. Discuss the proposed structure with a New York attorney and tax adviser before signing a contract.
Looking for an Investor-Friendly NYC Building?
Use our buyer inquiry form to share your budget, preferred neighborhoods, financing plans, and rental strategy.
Can Foreign Buyers Purchase NYC Co-ops or Condos?
Foreign buyers can purchase both, but condos are normally easier.
A condo may be more practical because it commonly offers:
- Fewer owner-occupancy restrictions
- Greater acceptance of entity ownership
- No co-op-style financial interview
- More flexible subletting
- A wider resale market
A co-op may require U.S. tax returns, domestic assets, employment documentation, or substantial post-closing liquidity. These requirements can be difficult for buyers whose income and assets are primarily outside the United States.
Foreign owners must also consider U.S. income-tax reporting and FIRPTA rules when selling. The IRS states that dispositions of U.S. real-property interests by foreign persons are generally subject to FIRPTA withholding. Review the IRS FIRPTA guidance.
International buyers should obtain cross-border tax and legal advice before choosing an ownership structure.
What Is a Condop?
A condop usually describes a building in which a condominium structure contains separate units, with one unit operated as a residential cooperative and another unit or units used for commercial or other purposes.
A buyer in the residential portion normally purchases co-op shares, not a deeded condo apartment.
Some condops use more flexible approval and subletting policies than traditional co-ops, but the word “condop” does not guarantee investor-friendly rules. Investors must review the actual ownership documents and rental policy.
Which Is Better for Investment in Manhattan?
For a pure rental strategy, a Manhattan condo is usually the more flexible choice.
Manhattan co-ops can offer:
- Attractive locations
- Larger prewar layouts
- Lower acquisition prices
- Established buildings
- Potential value compared with nearby condos
However, many prestigious co-ops prioritize owner occupancy and impose strict financial or subletting requirements.
A Manhattan condo may command a premium because it can appeal to investors, foreign buyers, pied-à-terre owners, and purchasers using entities.
The right comparison is not “Manhattan co-op versus Manhattan condo” in the abstract. Compare properties within the same neighborhood, size range, condition, and building tier.
Which Is Better in Brooklyn and Queens?
Brooklyn and Queens have substantial condo inventory, including newer developments that may accommodate investment ownership more readily than traditional Manhattan co-ops.
Investors should still evaluate:
- Sponsor reputation
- Offering-plan projections
- Tax-abatement expiration
- Common-charge history
- Reserves
- Unit mix
- Investor concentration
- Rental competition
- Construction warranties
- Unsold sponsor units
- Planned nearby development
A newer condo can offer appealing amenities and rental demand but may carry a premium price and initially understated operating expenses. A resale condo provides a longer record of expenses, assessments, and actual building performance.
Neighborhood selection should rely on measurable factors such as acquisition price, lawful rent potential, vacancy, transit access, inventory, taxes, new supply, and resale activity—not assumptions about the people who live there.
How to Calculate Potential Investment Return
Do not judge a property only by expected appreciation. Begin with the income and expenses you can reasonably document.
Net operating income
A simplified calculation is:
Annual rental income − vacancy allowance − operating expenses = net operating income
Operating expenses may include:
- Maintenance or common charges
- Property taxes
- Insurance
- Repairs
- Management
- Sublet fees
- Leasing expenses
- Owner-paid utilities
Mortgage payments and income taxes are generally evaluated separately from property-level net operating income.
Capitalization rate
Net operating income ÷ total acquisition cost = capitalization rate
Total acquisition cost should include the purchase price, closing costs, immediate renovations, and other expenses necessary to make the apartment rentable.
Cash-on-cash return
Annual pre-tax cash flow ÷ total cash invested = cash-on-cash return
This calculation reflects financing but remains sensitive to vacancy, unexpected repairs, assessments, and changes in rent.
An investment projection should include a conservative case rather than assuming uninterrupted tenancy and rapid appreciation.
Cost of living in different NYC boroughs
When Can a Co-op Be the Better Investment?
A co-op may be the better choice when:
- The purchase discount is meaningful.
- The building permits sufficient subletting.
- The investor intends to occupy the unit initially.
- Monthly maintenance is reasonable.
- The building has strong reserves.
- No major assessment is expected.
- The apartment has clear resale appeal.
- The investor qualifies comfortably under board rules.
- The expected holding period is long enough to absorb transaction costs.
A co-op is usually unsuitable for a pure rental plan when the investor must occupy it for years before renting or may sublet only briefly.
When Is a Condo the Better Investment?
A condo is generally more suitable when:
- Rental income is the primary objective.
- The buyer wants recurring leasing flexibility.
- An LLC or trust will purchase the property.
- The buyer lives outside New York or outside the United States.
- Resale liquidity is important.
- The property will be used as a pied-à-terre.
- The investor wants a less intrusive purchase process.
- The buyer can absorb the higher price and closing costs.
The condo still needs to pass a financial review. Flexibility does not make an overpriced or poorly managed building a sound investment.
Due-Diligence Checklist for NYC Investors
Before making an offer, verify:
Rental rules
- Is subletting permitted?
- Is owner occupancy required first?
- How many years may the unit be rented?
- Are sublet fees charged?
- Is there a minimum lease term?
- Must each tenant receive board approval?
Building finances
- How large is the reserve fund?
- Does the building have an underlying mortgage?
- Are operating expenses rising?
- Are assessments planned?
- Are major repairs pending?
- Is litigation underway?
- Is insurance adequate?
Purchase and financing
- What down payment does the building require?
- What liquidity must remain after closing?
- Does the building allow investor loans?
- Can an LLC, trust, or foreign buyer purchase?
- Will the lender approve the building?
Investment performance
- What rent is supported by recent comparable leases?
- How long do comparable rentals remain available?
- What vacancy allowance is realistic?
- What are the complete acquisition costs?
- What is the projected net operating income?
- How sensitive is the return to an assessment or rent reduction?
- Who is the likely resale buyer?
Frequently Asked Questions
Is it better to buy a co-op or condo in NYC for investment?
A condo is usually better for a rental-focused investment because it generally offers more flexible leasing, ownership, and resale. A co-op may work when its price is attractive and its rental rules support the intended strategy.
Are NYC co-ops a good investment in 2026?
Some can be. Evaluate the specific price, monthly maintenance, building finances, subletting policy, assessment exposure, and likely resale market. The year alone does not determine whether a co-op is a good investment.
Why are NYC co-ops cheaper than condos?
Co-ops generally have more restrictive financing, ownership, rental, and resale requirements. Those restrictions reduce the number of eligible buyers and investors.
Do NYC condos appreciate faster than co-ops?
Condos may benefit from a wider buyer pool, but appreciation depends on the individual property, price, location, condition, carrying costs, and market cycle.
Are NYC co-ops harder to sell?
They can be because the next buyer may need to satisfy detailed board, financing, down-payment, liquidity, and occupancy rules.
Which has better resale value?
Condos generally provide stronger resale flexibility. A well-priced co-op in a strong building can still produce a successful resale.
Which has higher monthly costs?
Co-ops often show higher maintenance because property taxes may be included. Condo owners normally pay common charges and property taxes separately. Compare the complete monthly amount.
Can I rent out my NYC co-op?
Only if the proprietary lease and building policies permit it. Check owner-occupancy requirements, rental caps, permitted duration, fees, and approval procedures.
Can I rent out my NYC condo?
Usually, but the declaration and bylaws may impose lease terms, application procedures, fees, and other restrictions.
Can I operate a short-term rental from a condo?
Owning a condo does not override NYC short-term rental law or building rules. Renting an entire apartment for fewer than 30 days is generally prohibited.
Do co-op buyers pay mortgage recording tax?
A traditional co-op loan generally does not incur mortgage recording tax because it is secured by personal property rather than a recorded mortgage against real property.
Do co-op buyers need title insurance?
Co-op transactions generally use lien and UCC searches rather than conventional condo title insurance. Attorneys and lenders determine the appropriate protections for each transaction.
Can foreigners buy NYC co-ops?
Yes, but the building’s documentation, financial, and residency requirements can make approval difficult. Condos are generally more accessible to international buyers.
Should a first-time investor buy a co-op or condo?
A condo is usually simpler for a first-time rental investor. A co-op may be appropriate for an owner-occupant who wants a lower entry price and may rent later.
Is a condop better than a traditional co-op?
It can offer more flexible policies, but “condop” does not guarantee investor-friendly terms. Review the governing documents before making an investment decision.
Final Verdict: Co-op or Condo?
For a pure NYC real-estate investment, a condo is usually the stronger choice. The higher purchase price and closing costs buy greater flexibility to rent, resell, finance, and structure ownership.
A co-op can offer better value for an owner-investor who plans to live in the apartment, can satisfy the board’s financial requirements, and has confirmed that the building’s subletting policy supports future plans.
Do not choose based solely on the label. The best investment is the individual property where the purchase price, lawful rental income, recurring expenses, building condition, financing, and exit strategy work together.
Best Time to Buy a Home in NYC
Ready to Compare NYC Investment Properties?
Tell us your budget, preferred neighborhoods, financing plans, and rental goals through our buyer inquiry form.
This article provides general real-estate information and is not individualized legal, tax, investment, or financial advice. Building rules and transaction costs must be verified for the specific property.